 Analysis by Appwee
I think the most useful way to judge an early-pay app is to ask what problem you want it to solve. If a bill is due before your next paycheck, getting access to wages you have already earned may help bridge that timing gap. If the underlying issue is that regular expenses exceed regular income, though, moving payday forward won’t fix it. That distinction is the key to using EarnIn thoughtfully rather than treating it like extra income.
Start with the timing problem
Before signing up, I’d look at the specific expense you’re trying to cover and when money is expected to arrive. An early transfer can make sense for a one-off mismatch, such as a utility bill landing a few days before payday. It is less helpful if you need to draw money early every pay period just to cover ordinary spending, because the next check then has less room to handle the next set of bills.
For a realistic example, imagine an hourly worker whose hours are already worked but whose paycheck is still several days away. A necessary expense arrives sooner than expected. The useful question is not simply “Can I get money now?” but “Will the next paycheck still cover rent, food, transport, and other commitments after this amount is taken into account?” I’d answer that before making a transfer, and I’d treat the amount as part of the coming paycheck rather than as a bonus.
A repeatable routine beats last-minute checking
Once the account is set up, I’d make checking recorded work time part of a regular routine. That gives you a chance to notice a mismatch while there is still time to correct it, instead of discovering it when you urgently need cash. Keep your own record of shifts or hours as well; it is a simple way to compare what you expect to have earned with what the app recognizes.
I’d also decide in advance what counts as a genuine reason to use an advance. A short personal rule—such as reserving it for an essential bill or an unavoidable expense—can help prevent convenience from turning into a habit. If you do use it, note the amount and the effect on the next paycheck in the same budget you use for rent and other bills. That small bit of bookkeeping makes repeat use easier to evaluate honestly.
How it fits among cash-flow options
EarnIn sits in a different place from a credit card, overdraft facility, or personal loan. Those options may involve borrowing against a credit limit or taking on a repayment obligation, while early-pay access is framed around wages already earned. The practical trade-off is that this is not a fresh source of income: receiving some of your pay sooner means planning around the smaller remainder later. I would compare the timing, cost, and repayment consequences of any alternative available to me rather than assuming one choice is automatically cheaper or safer.
If you have savings set aside for emergencies, using those may be simpler than accessing pay early, provided you can rebuild the cushion without creating another problem. If the expense is flexible, moving its due date or waiting until payday may be better still. For a persistent shortfall, I’d first review recurring bills and income, or seek qualified financial guidance; repeatedly shifting the timing of wages can otherwise conceal a budget that needs a more durable change.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
What to check before relying on it
Access depends on the app being able to recognize your employment and earnings, so I wouldn’t assume every job or pay arrangement will work identically. If your hours change often, check that the amounts shown match your records before making plans around them. A new work schedule, payroll change, or delayed time information can make an expected amount less dependable for a time-sensitive bill.
It is also sensible to review the current terms and available choices inside the app before requesting money. The amount you can access is subject to limits, and a daily ceiling is not the same as a promise that the maximum will be available whenever you open the app. I’d plan around the amount actually presented to me, not build a bill-payment plan around the headline maximum.
Who is likely to get the most from it?
I can see this being most useful to someone with dependable earned wages, a temporary gap between an expense and payday, and enough room in the next paycheck to absorb an early transfer. It is less suited to someone whose income is unpredictable, who cannot comfortably cover later bills after taking money early, or who wants a long-term solution to ongoing debt. In those situations, a savings buffer, a conversation with a bill provider, or a broader budgeting plan may be a better first move.
The app is free to download and is listed for Everyone. Activehours Inc. is its developer; it has a 4.7 average from around 286,000 ratings, and has been installed over 10 million times. It is a finance app, not a replacement for a bank account or a complete budgeting system. Those figures may offer a sense of how widely it is used, but they don’t tell me whether it will fit a particular employer, pay schedule, or personal budget.
On Android, the listed minimum operating system is version 8.0, and the current version is 16.32. The app has been available since January 21, 2014. I’d still check that my device and account setup suit the current app before relying on it for a deadline. Its basic appeal is straightforward, but the value depends on whether the timing works in your own situation.
If I were trying it, I’d begin with a small, planned use rather than treating early access as part of every paycheck. I’d verify the earnings information, check how the next pay cycle will look, and keep an eye on whether I’m reaching for it more often than intended. That gives me a practical way to see whether the convenience is helping or merely moving financial pressure from one date to another.
Waiting for payday can be stressful, and having another option can matter. My view is that EarnIn is most sensible as a short-term cash-flow tool for earned wages, used with a clear reason and a plan for the next check. If you can keep those boundaries, it may be a useful option to consider; if the same shortfall keeps returning, I’d look beyond early access for a more lasting answer.
If you’re anything like me, waiting for payday can sometimes feel like an eternity. Whether you’ve got bills stacking up or you just want a little extra cash for the weekend, EarnIn is here to help. This nifty app is changing the way we think about paychecks, allowing you to access the money you’ve already earned before your official payday. Let’s dive into how EarnIn works and whether it’s worth downloading.
How EarnIn Works
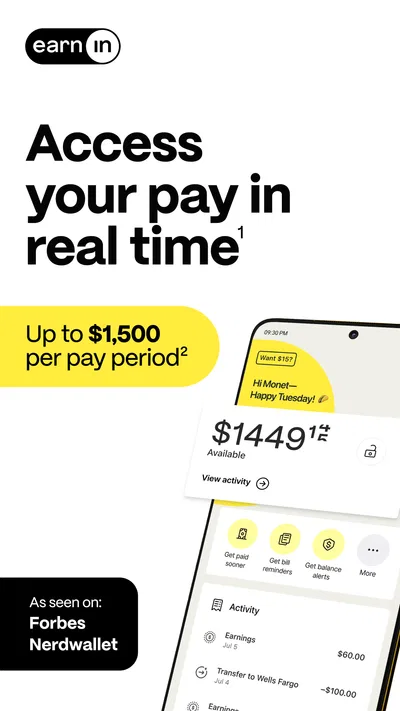
So, here’s the scoop. EarnIn lets you cash out up to $100 a day from your upcoming paycheck. The app works by tracking the hours you’ve worked through a timesheet, which you can update manually or link with your employer’s payroll system. Once verified, you can transfer funds directly to your bank account. Pretty neat, right?
The best part? There’s no interest or mandatory fees. Instead, EarnIn operates on a pay-what-you-think-is-fair tipping model. You can choose to tip from $0 to $14 per transaction, which goes towards supporting the app’s operations. This flexibility is a breath of fresh air in a world where hidden fees seem to lurk around every corner.
Features Worth Noting
Besides the core feature of early pay access, EarnIn offers some additional perks that make it stand out. The Balance Shield feature is a lifesaver, especially if you’re prone to overdrafting. It alerts you when your bank balance is low, helping you avoid those pesky overdraft fees.
Then there’s the Health Aid feature, which allows you to set aside funds specifically for medical expenses. This is a fantastic way to ensure you’re prepared for any unexpected medical bills without disrupting your usual budget.
Getting Started
Setting up EarnIn is pretty straightforward. You’ll need to download the app from the App Store or Google Play and create an account. From there, you’ll provide your employment details and connect your bank account. Make sure your employer supports direct deposit, as this is a necessity for the app to function properly.
Once everything’s set up, you can start tracking your hours and cashing out. It’s a smooth process, and the app’s interface is intuitive, even for those who aren’t tech-savvy. The dashboard is user-friendly, allowing you to monitor your earnings and manage your finances with ease.
Is EarnIn Right for You?
Let’s talk about who might benefit the most from using EarnIn. If you’re someone who lives paycheck to paycheck or occasionally finds yourself in need of a financial boost before payday, this app could be a game-changer. It’s especially useful for hourly workers who might have variable income due to fluctuating hours.
However, if you’re well-disciplined with your budgeting and don’t face short-term cash flow issues, you might not find as much utility from the app. Remember, while it’s convenient to access your earnings early, it’s important to use it responsibly. Over-reliance on early access to pay can lead to potential budgeting issues down the line.
Final Thoughts
All in all, EarnIn is a valuable tool for anyone looking to break free from the traditional two-week payday cycle. With its user-friendly interface, flexible tipping model, and useful features like Balance Shield, it’s no wonder the app has gained popularity among users seeking financial flexibility.
While it’s not a substitute for a solid financial plan, it’s a great supplemental tool to help manage cash flow. If you’re curious, I’d say give it a shot. After all, in the world of finances, having options is always a good thing.
EarnIn: Why Wait for Payday? Pros and Cons
- Instant access to earned wages.
- No hidden fees or interest charges.
- User-friendly interface and navigation.
- Integrates with most banks easily.
- Cash-out requests processed quickly.
- Limited cash-out amounts per pay period.
- Requires consistent employment verification.
- Not available in all states.
- May encourage poor budgeting habits.
- Dependent on direct deposit setup.
EarnIn: Why Wait for Payday? Frequently Asked Questions
What is EarnIn and how does it work?
EarnIn is a financial app that allows users to access a portion of their earned wages before payday. Users can connect their bank account and provide employment details, enabling the app to track hours worked. Once verified, users can cash out a portion of their earned income, which is then deducted from their next paycheck.
Are there any fees associated with using EarnIn?
EarnIn does not charge mandatory fees or interest. Instead, it operates on a voluntary tipping model. Users can choose to tip an amount they feel is fair for the service provided. This flexibility can be appealing to those who prefer avoiding traditional payday loan fees and high-interest rates.
Is EarnIn safe to use for accessing my paycheck early?
Yes, EarnIn is designed with user security in mind. The app uses bank-level encryption to protect your personal and financial information. It requires minimal access, such as bank account and employment details, to function properly. Users should always ensure they are downloading from official app stores to avoid fraudulent versions.
How much money can I cash out with EarnIn?
The amount you can cash out with EarnIn varies based on factors like your pay cycle and the hours you've worked. Initially, users may access up to $100 per pay period, which can increase as the app gathers more data on your income patterns and reliability. It's a helpful tool for managing unexpected expenses.
What are the requirements to use EarnIn?
To use EarnIn, users must have a steady paycheck, a bank account, and a smartphone. Additionally, you need to provide employment information and work hours for the app to verify your earnings. The app is compatible with most bank accounts, but users should ensure their employer supports direct deposit to facilitate transactions.
Gallery